Trending now
Bombay HC Sets Aside ₹52.61 Crore Property Valuation in Stamp Duty Dispute
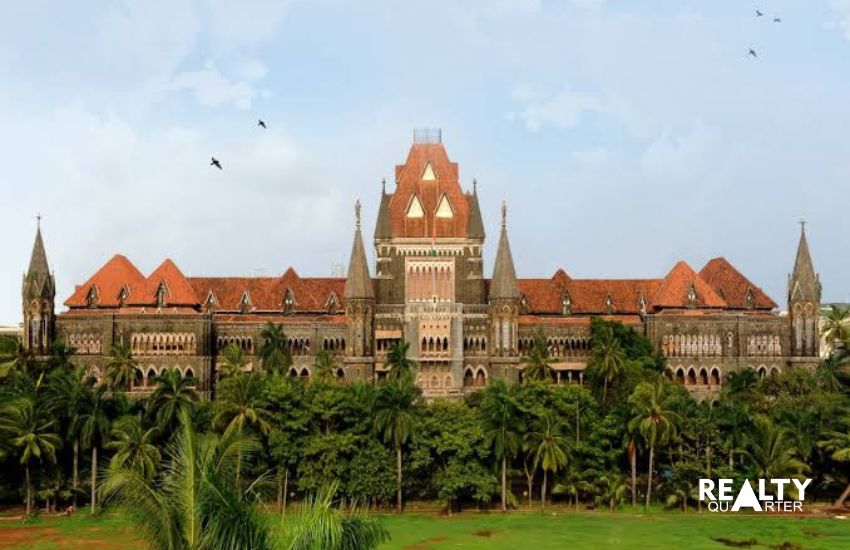
Mumbai, September 17, 2026: The Bombay High Court has set aside a ₹52.61-crore property valuation that led to a ₹2.03-crore stamp-duty demand, ruling that uncertain future redevelopment benefits cannot be treated as guaranteed value while determining property valuation.
The ruling has implications for Mumbai’s redevelopment market, where development rights, FSI and TDR can significantly influence property transactions. The court emphasised that potential future benefits must be considered alongside the property’s actual condition, legal complications and the risks involved in developing it.
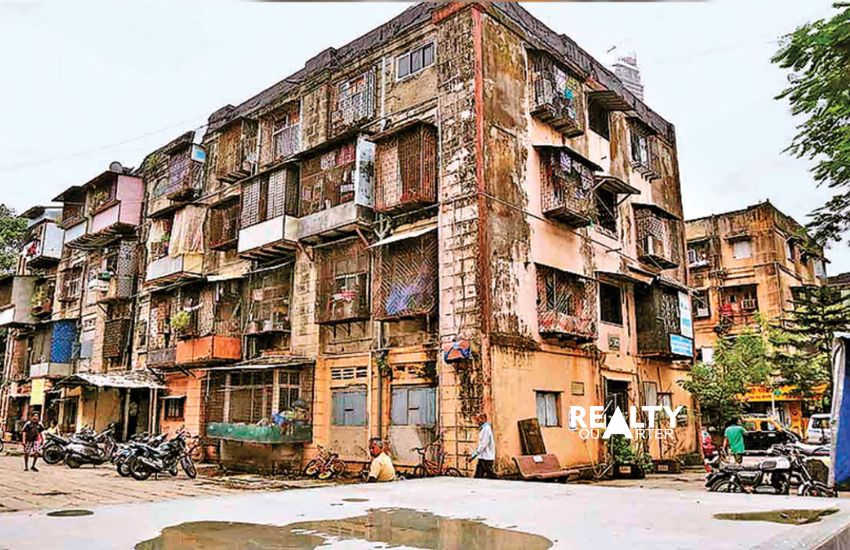
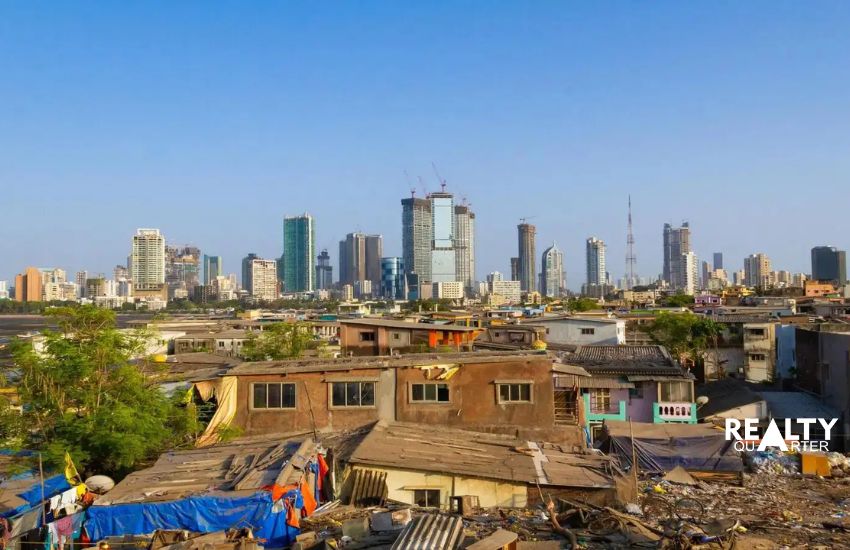
The case involved Transcon Sheth Creators Private Limited and another and concerned a conveyance covering 17 plots. The transaction was executed in 2007, when parts of the property were occupied by slum dwellers.
Dispute Over Property Valuation
The Collector of Stamps had initially determined the property’s valuation at approximately ₹12 crore, on which stamp duty of ₹60 lakh was paid.
The valuation was later revised to approximately ₹52.61 crore. This resulted in a demand for around ₹2.03 crore in additional stamp duty, apart from penalty.
A central issue before the High Court was whether potential benefits linked to Slum FSI and Slum TDR could be used to substantially increase the property’s valuation for stamp-duty purposes.
The petitioners argued that these were future possibilities rather than development rights available to the property at the time of the 2007 transaction.
Court Considers Development Risks
Justice Amit Borkar examined the circumstances surrounding the property and noted that its development prospects were subject to considerable uncertainty.
The property had been purchased on an “as-is-where-is” basis and was affected by various complications, including litigation, encroachments, claims and restrictions relating to development.
The court observed that these factors could affect what a purchaser would actually be prepared to pay. Therefore, potential redevelopment benefits could not be considered separately from the costs, risks and obstacles attached to the property.
Future development potential may have a bearing on property valuation, but it cannot automatically be treated as an assured benefit when the relevant development rights or approvals have not materialised.
₹52.61-Crore Valuation Set Aside
The High Court found that the revised property valuation was not adequately supported by evidence showing that the property’s legal and development-related burdens had been properly accounted for.
The court also noted the absence of a comparable transaction involving a property with similar circumstances to justify the substantially higher valuation.
The High Court therefore quashed the ₹52.61-crore property valuation and the consequential ₹2.03-crore deficit stamp-duty demand.
The original property valuation of approximately ₹12 crore, along with stamp duty of ₹60 lakh, was restored.
Implications for Mumbai Redevelopment
The judgment is relevant to Mumbai’s redevelopment and land market, particularly where future FSI, TDR or redevelopment rights form an important part of a property’s expected commercial value.
For developers, landowners and purchasers, the ruling highlights the need to distinguish between development rights that are presently available and benefits that may arise only in the future.
The judgment does not mean that future redevelopment potential can never be considered. Rather, it indicates that such potential must be assessed in the context of the property’s actual circumstances and the uncertainties involved in realising it.
The decision reinforces the principle that potential future development benefits cannot automatically be treated as guaranteed value for property valuation purposes.
Case: Transcon Sheth Creators Private Limited & Anr. v. State of Maharashtra & Anr., Writ Petition No. 10725 of 2015.
Tags: 17 plots Mumbai, as-is-where-is property, Bombay HC judgment, Bombay High Court property valuation, Collector of Stamps, development potential valuation, FSI property valuation, future redevelopment potential, Mumbai real estate law, Mumbai redevelopment, property legal dispute, property valuation dispute, property valuation Maharashtra, redevelopment rights Mumbai, Slum FSI, Slum TDR, stamp duty dispute Mumbai, stamp duty Maharashtra, TDR property valuation, Transcon Sheth Creators, Transcon Sheth Creators case, Writ Petition No. 10725 of 2015, ₹2.03 crore stamp duty demand, ₹52.61 crore property valuation


Our Esteem Clients:
Channel Partner Associations:
Our Partners:
Our Supporters: